The Reimbursement Gap: Running a Company EV on Your Own Driveway in 2026
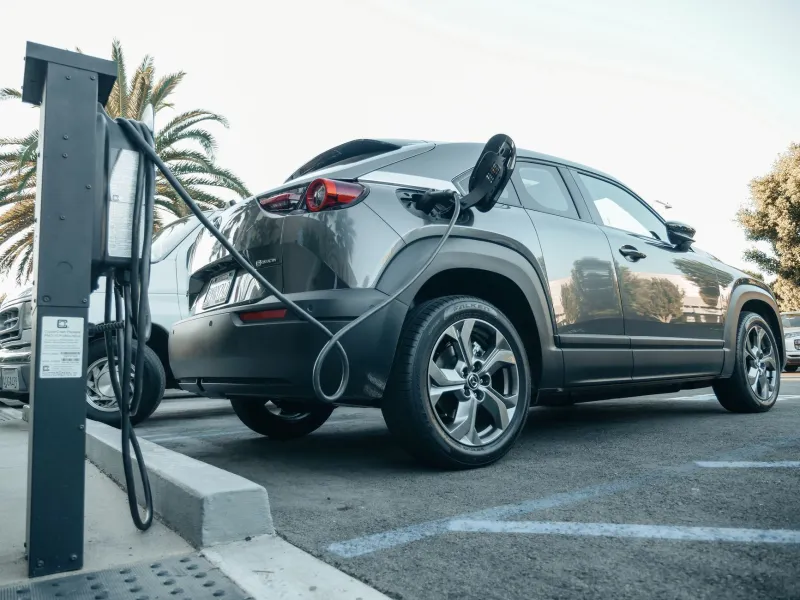
A company car is rarely the freebie it appears to be on the payslip. The benefit-in-kind charge is visible enough, but the charging costs hide in plain sight: the electricity that goes into the battery is usually bought by the driver, on the driver's own tariff, from the driver's own meter. What comes back is a mileage rate set by HMRC, and the distance between that rate and reality is where company EV drivers quietly lose money.
The assumption that costs money
Fleets and drivers tend to work from a simple premise: the company pays for the car, so the company pays for the fuel. For petrol and diesel that holds up, because fuel cards and mileage rates have decades of institutional practice behind them. For electricity it does not, or at least not reliably. Most company EV drivers charge at home, overnight, on a domestic supply. Reimbursement is then handled either through a flat per-mile rate or, less commonly, through an evidenced actual-cost claim.
The first of those is where the trouble starts.
Four pence a mile and the weight it carries
HMRC's advisory electricity rate (AER) for fully electric company cars has sat at 4p per mile for years, having been introduced in 2018 and left untouched since. Employers use it to reimburse business mileage free of income tax and National Insurance, and it carries the considerable advantage of requiring no receipts. The rate is advisory rather than mandatory; a fleet can pay a different figure provided it can show the amount reflects actual cost.
The problem is arithmetic. A typical UK home tariff in 2026 sits somewhere in the mid-twenties of pence per kilowatt-hour. An efficient family EV returns perhaps 3.5 miles per kWh in mixed conditions, and charging losses of around ten per cent mean the real-world figure is nearer 3.2. At 25p per kWh, that is roughly 7.8p per mile of electricity, very nearly double what the AER returns.
The shortfall, worked through
Take a driver covering 8,000 business miles a year on a standard variable tariff. Reimbursed at 4p, they receive £320. Their actual electricity cost, at 7.8p per mile, is around £624. The gap is just over £300, and it is borne entirely by the driver. This is not a rounding error; it is roughly the price of a set of tyres each year.
Add the miles that are never reimbursed at all, commuting, school runs and weekend trips among them, and the household electricity bill carries an even larger share of the car's running cost. Company car tax may be light for electric vehicles, but the fuel bill has simply moved from the forecourt to the kitchen wall.
When a cheap overnight tariff flips the maths
The picture inverts for drivers on a dedicated EV tariff. Off-peak rates of 6p to 8p per kWh are widely available, and a driver charging exclusively within that window pays closer to 2p to 2.5p per mile. Reimbursed at 4p, they make a modest surplus.
That surplus is not, in itself, a tax problem. AER payments are accepted without evidence, so an employer using the advisory rate does not have to claw back the difference. But drivers should not mistake a favourable tariff for a general rule. The rate works for the well-organised night-charger and works against everyone on a default tariff, which in most households is still the majority.
Salary sacrifice and the wider bill
Most company EV drivers now arrive via salary sacrifice rather than a traditional company car list. The appeal is straightforward: the car is leased from gross pay, so income tax and employee National Insurance are saved on the sacrificed amount, and the benefit-in-kind charge for a zero-emission car remains low. For the 2026/27 tax year the appropriate percentage for electric vehicles is 4 per cent, so a £45,000 EV produces a taxable benefit of £1,800, or £360 a year for a basic-rate taxpayer and £720 for a higher-rate one.
Compare that with a petrol car of similar list price, taxed at a far higher percentage, and the advantage is plain. But salary sacrifice changes the charging question rather than answering it. The scheme covers the lease, insurance and servicing; it does not cover the electricity, unless the employer explicitly builds a charging allowance into the arrangement. Drivers should read the scheme documentation for exactly that.
Charging at the workplace is a different matter
Where an employer provides charging at the office, the tax position is generous: electricity supplied for workplace charging, and the chargepoint itself, fall outside benefit-in-kind. Plugging in at work is effectively tax-free.
Free of tax is not the same as free of charge. Some employers meter workplace charging and recharge employees at cost, often through an app or RFID card; others absorb it as a staff benefit. Neither approach is unreasonable, but the two produce very different annual bills for a driver who can charge at work five days a week.
What to do about it
The single most useful step is to ask payroll which reimbursement method applies and whether an actual-cost claim is available. Many fleets will accept a smart charger export or a home electricity statement showing the kWh drawn by the car; where an employer will pay evidenced cost rather than the flat rate, a low-mileage driver on an expensive tariff is usually better off.
Second, keep records. A smart charger that logs sessions by date and kWh turns a speculative claim into a straightforward one, and it also gives the driver a clear view of what the car actually costs to run.
Third, check the tariff before the car arrives, not after. The difference between a default variable rate and a well-chosen overnight tariff is larger than the difference between most competing lease quotes, and it is the driver, not the fleet manager, who captures or loses that margin.
The company car has not stopped being a good deal for electric vehicles. It has simply become a deal whose terms are set partly by HMRC and partly by the driver's own electricity supplier. Understanding which is which is the difference between a car that pays its way and one that quietly drains the household account.